Indian Full-Service Restaurants (FSR) Market

Market Overview
• Full-Service Restaurants (FSR) comprise dining experiences that combine food with social occasions, from neighbourhood dhabas and mid-casual Indian restaurants to premium fine-dining establishments in metros.1
• FSR is the largest foodservice restaurant segment at 49.8%, followed by Fast Food (24.1%), Limited Service (16.5%) and Special Food Service (9.6%).1
• Restaurants can also be segmented by service type (dine-in, takeaway and delivery), outlet model (independent vs. chain), and location (Metro vs. Tier-2 cities).3

Source: IMARC, 20261
Market Size & Growth
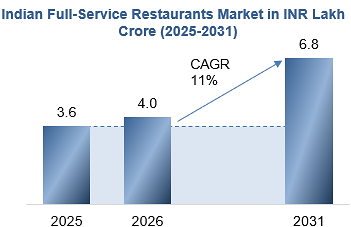
• India full-service restaurants market: Expected to grow from INR 3.6 lakh crore (USD 37.9 billion) in 2025 to INR 4.0 lakh crore (USD 42.1 billion) in 2026 and is forecast to reach INR 6.8 lakh crore (USD 70.8 billion) by 2031 at an 11% CAGR over 2026–2031.3
• India FSR market growth is significantly ahead of the global full-service restaurant market, with an approximately 11% CAGR versus 3.3% globally. 2
Source: Mordor Intelligence, 20263
Market Segmentation
• Independent vs. chain outlets: Independent outlets account for 73.2% of FSR revenue.3
• Dine-in vs. delivery/takeaway: Dine-in contributes 65.1% of market revenue.3
• Standalone restaurants vs. lodging-based FSRs: Standalone restaurants hold a 47.6% share.3
• Metro vs. Tier-2 cities: Mumbai, Delhi, Bengaluru, Hyderabad and Pune lead the market.3

Source: Mordor Intelligence, 20263
Growth Drivers
 Source: Mordor Intelligence, 20262,3
Key Industry KPIs
• Sales & customer spend: Average order value (AOV).4
• Customer retention: Customer return rate,5 indicating customer loyalty and recurring business.
• Capacity & utilization: Table turnover rate, revenue per square foot and peak-hour efficiency score,5 measuring how effectively seating capacity and operating hours are utilized.
• Channel & operational efficiency: Channel mix and staff productivity index,4 assessing revenue contribution across channels and labour efficiency.
• Unit economics: Gross profit margin, operating profit margin and break- even point,6 evaluating cost management, profitability and the sales level required to cover operating costs.
Regulatory Requirements & Certifications
 Source: Bill Feeds, 20267
Top 5 Indian Full-Service Restaurant Companies - Competitive Positioning
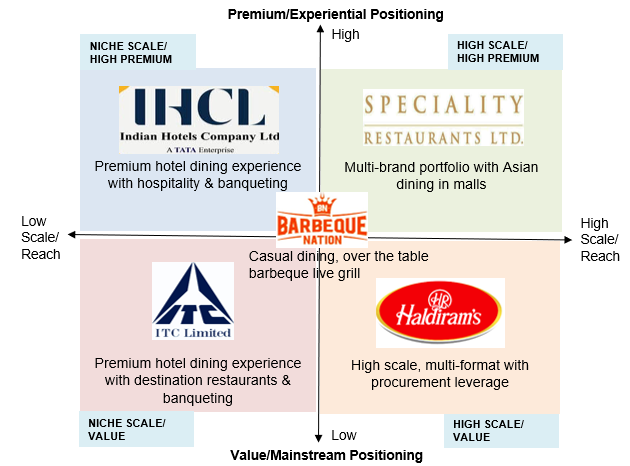
Source: Mordor Intelligence, 20268
Pricing, Margins & Cost Structure
• Gross Profit Margin: A gross margin of 65-72% is typical for Indian restaurants.9
• Fine Dining (Net Margin: 12-18%): Fine dining restaurants in India have lower net margins despite charging the highest prices. Reasons:9
- Prime real estate in upscale neighbourhoods
- Larger trained staff
- Premium imported ingredients
- Expensive crockery and décor
- High marketing spends
• The Prime Cost Ratio: Labour + Food Cost: The best-run Indian restaurants keep their prime cost at 55-60%, leaving enough room to absorb rent, utilities, and other overheads while still being profitable.9
• The 10% Rent Rule: Rent should never exceed 10-12% of projected revenue.9
• EBITDA %: 8%–15% for healthy operations.10
Industry Benchmarks for Net Profit Margin
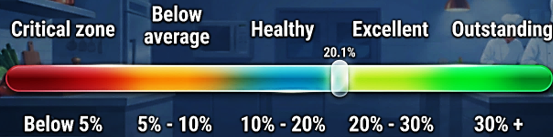
Source: DineOpen, 20269
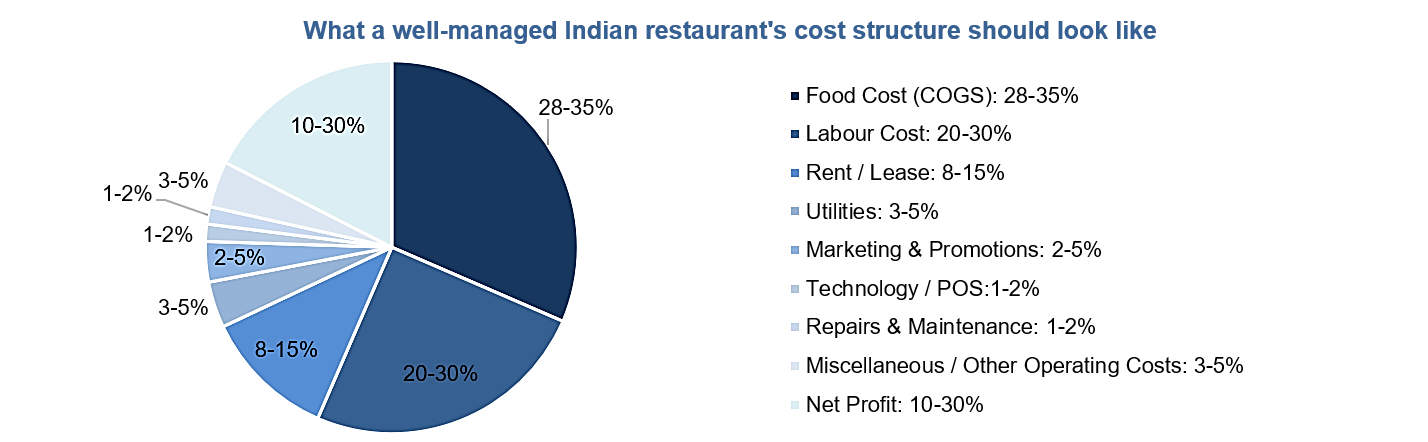 Source: DineOpen, 20269
Recent Developments
- India is on track to become the world's third-largest food-service market by 2028, overtaking Japan according to NRAI (National Restaurant Association of India)11
- Eating out has shifted from an occasional treat to a routine social and lifestyle activity, particularly among millennials and Gen Z. The share of household expenditure on restaurants and hotels rose to 2.3% in FY 2024, up from 2.1% in the previous year 12
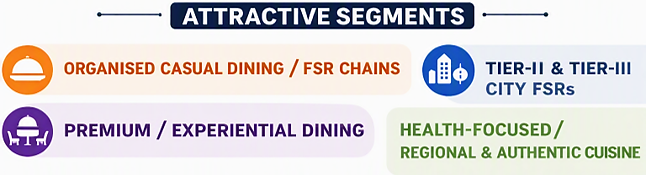
- Nearly 94% of operators plan to expand in Tier-II and Tier-III markets, with nearly 78% expecting to break even within 2 years 11
- The organized segment of the food-services industry is expected to grow at a CAGR of 13.2%, achieving a market share of 52.9% by 2028 12
- India’s F&B sector has already witnessed 83 deals and INR 14,923.2 crore (USD 1.56 billion) in YTD 2025, with investors backing health-focused, premium, and tech-enabled formats 11
Restaurants are getting rid of printed menus and replacing them with:
- QR code-based menus
- Digital boards
- Ordering systems that work with apps 12
Consumer Trends:
Key consumer trends shaping restaurant demand include:
• Cutting back on ultra-processed foods (94.2%) 11
• Supporting local farmers & producers (90.4%) 11
• The rise of clean & safe food choices (78.8%) – a hygiene-driven evolution 11
• The climatarian movement gains momentum (75.0%) – eating for the planet 11
• Traditional wisdom meets modern convenience 11
Regulatory & Policy Developments
Proposed GST Reform
• NRAI has proposed the introduction of a GST slab between 12% and 18% with Input Tax Credit (ITC). 13
• Existing GST rate remains 5% without ITC for restaurants not located within hotels having room tariffs above ₹7,500. 13
Commercial Lease GST
• NRAI has requested a review of Notification No. 09/2024 dated 8 October 2024 regarding GST on commercial leases through the Reverse Charge Mechanism (RCM). 13
Key Policy Reforms Requested by NRAI
• Creation of equitable e-commerce policies to ensure a level playing field. 13
• Simplification and standardisation of licences and NOCs. 13
• Permission for longer operating hours, including 24x7 operations.13
Structural Reforms Sought by NRAI
• Grant industry status to the foodservice sector. 13
• Establish a dedicated ministry or department for foodservice. 13
• Improve employee welfare and workforce development initiatives. 13
Recent Mergers & Acquisitions in the Indian Foodservice Market
Theobroma
• ChrysCapital acquired a 90% stake in Theobroma for INR 2,410 crore. 14
• The transaction is expected to strengthen investor confidence in the Quick Service Restaurant (QSR) market and support ChrysCapital's expansion ambitions in the sector.
Sky Gate Hospitality
• Devyani International acquired an 80.72% stake in Sky Gate Hospitality for INR 419.60 crore. 15
• Sky Gate Hospitality is known for brands such as Biryani By Kilo.
• The acquisition is expected to strengthen Devyani's premium dining and food delivery presence.
Restaurant Brands Asia (RBA)
• Inspira Global completed the acquisition of Restaurant Brands Asia Ltd. for INR 2,235 crore. 16
• Restaurant Brands Asia operates:
- Burger King India
- Burger King Indonesia
- Popeyes Indonesia
• Following the transaction, Inspira Global holds a 41.78% stake in Restaurant Brands Asia. 16
Porter’s 5 Force Analysis
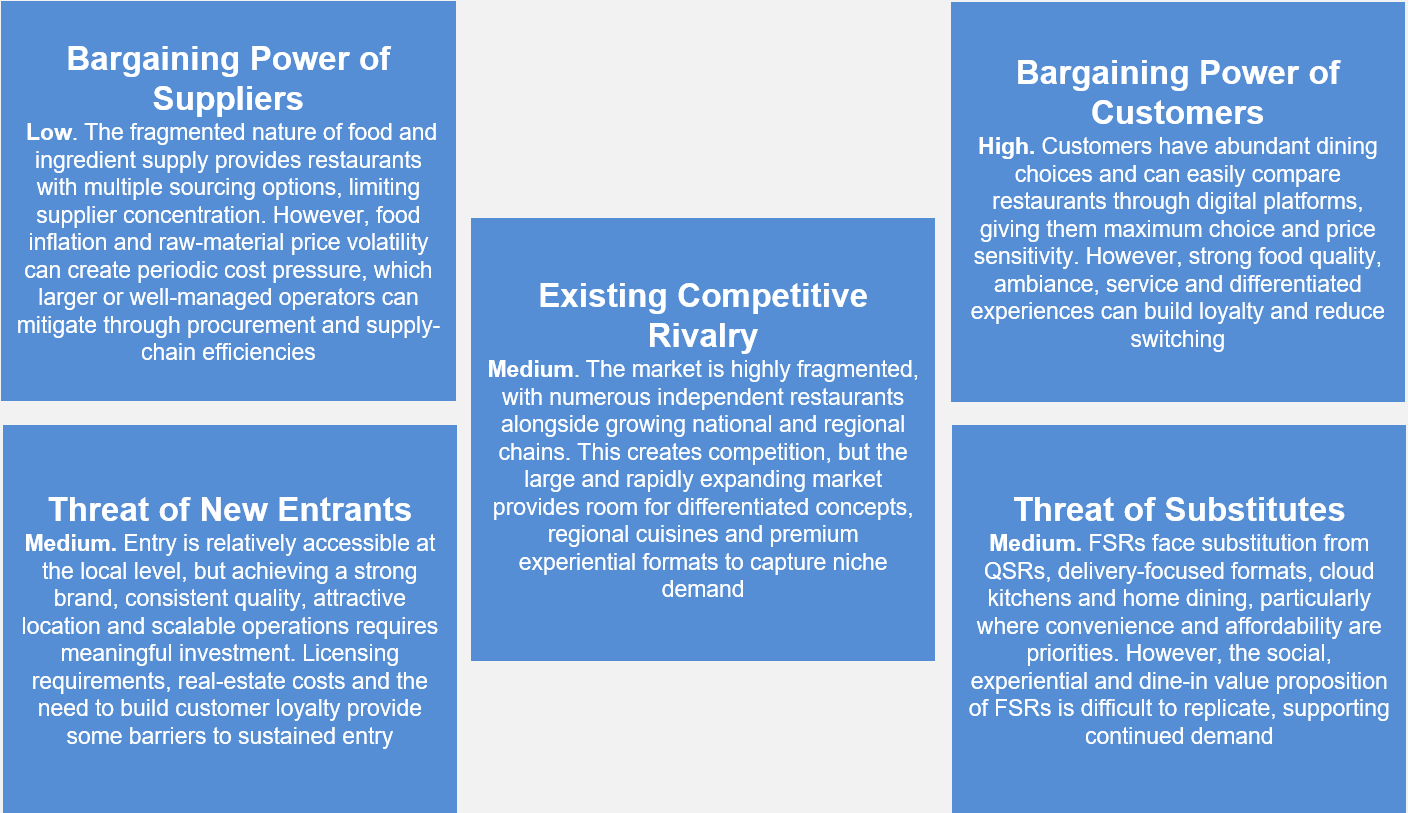
Bargaining Power of Suppliers
Low. The fragmented nature of food and ingredient supply provides restaurants with multiple sourcing options, limiting supplier concentration. However, food inflation and raw-material price volatility can create periodic cost pressure, which larger or well-managed operators can mitigate through procurement and supply-chain efficiencies.
Bargaining Power of Customers
High. Customers have abundant dining choices and can easily compare restaurants through digital platforms, giving them maximum choice and price sensitivity. However, strong food quality, ambiance, service, and differentiated experiences can build loyalty and reduce switching.
Existing Competitive Rivalry
Medium. The market is highly fragmented, with numerous independent restaurants alongside growing national and regional chains. This creates competition, but the large and rapidly expanding market provides room for differentiated concepts, regional cuisines, and premium experiential formats to capture niche demand.
Threat of New Entrants
Medium. Entry is relatively accessible at the local level, but achieving a strong brand, consistent quality, attractive location, and scalable operations requires meaningful investment. Licensing requirements, real-estate costs, and the need to build customer loyalty provide some barriers to sustained entry.
Threat of Substitutes
Medium. Full-service restaurants face substitution from QSRs, delivery- focused formats, cloud kitchens, and home dining, particularly where convenience and affordability are priorities. However, the social, experiential, and dine-in value proposition of FSRs is difficult to replicate, supporting continued demand.
Transaction Comparables
| Date | Target | Acquirer / Investor | Target Description | EV (in USD Millions) | EV/ Revenue | EV/ EBITDA |
Oct-24 |
Papa Murphy's Holdings, Inc. 17 |
MTY Food Group Inc. |
Franchisor and operator of the Papa Murphy's take-and-bake pizza chain, with franchised and company-owned restaurants across the U.S., Canada and UAE. HQ: Vancouver, Washington, USA. |
184 |
1.5x |
8.4x |
Feb-24 |
Bojangles', Inc. 18, 19 |
Durational Capital Management & The Jordan Company |
Restaurant operator and franchisor specializing in Southern-style chicken, made-from-scratch biscuits, breakfast and sides. HQ: Charlotte, North Carolina, USA. |
756 |
1.4x |
12.6x |
Jul-25 |
Denny's Corporation 20, 21 |
TriArtisan Capital Advisors, Treville Capital Group & Yadav Enterprises |
Full-service diner chain offering breakfast, burgers and American comfort food through company-owned and franchised restaurants. HQ: Spartanburg, South Carolina, USA. |
620 |
1.4x |
8.0x |
| Median | 1.4x | 8.4x |
Trading Comparables
| (In INR Billion, As on 8th of September) | Enterprise Value (EV) | Revenue (TTM) | EBITDA (TTM) | EV / Revenue | EV / EBITDA |
| Company | |||||
Coffee Day Enterprises Limited 22 |
9 |
11 |
4 |
0.8x |
2.4x |
Sapphire Foods India Limited 23 |
86 |
32 |
5 |
2.7x |
17.1x |
Speciality Restaurants Limited 24 |
6 |
5 |
1 |
1.2x |
6.0x |
Vikram Kamats Hospitality Limited 25 |
1 |
1 |
0 |
2.5x |
9.8x |
| Median | 1.9x | 7.9x |
Sources:
- India Food Service Market
- Global Full-Service Restaurants Market
- Indian Full-Service Restaurants Market
- Restaurant Analytics Metrics
- 5 Restaurant Metrics
- Restaurant KPIs
- Restaurant Registrations
- Top Players
- Restaurant Profit Margins
- Industry Ratios for Restaurants
- Restaurant India Article
- Exploring the Segments
- NRAI Report
- Chryscapital Deal
- Devyani Deal
- Inspira Global Deal
- Papa Murphy's Holdings, Inc.
- Bojangles', Inc. Financials
- Bojangles', Inc. Deal
- Deal Value of Denny's Corporation
- Financials of Denny's Corporation
- Coffee Day
- Sapphire
- Speciality
- Vikram Kamats